For business owners seeking innovative funding solutions, Rotating Savings and Credit Associations (ROSCAs) present an invaluable opportunity. These informal financial cooperatives allow members to save and access credit through community efforts, fostering a robust network of trust and collaboration. By examining how to participate in ROSCAs, understanding their structure, and locating community resources, business owners can leverage these groups to enhance their financial stability and growth potential. In the following chapters, we’ll explore each of these facets to underline the significance of ROSCAs in supporting local entrepreneurship.
Locating and Joining ROSCAs Near You: A Practical Path Through Community Networks
ROSCAs, or rotating savings and credit associations, sit at the intersection of finance and trust. They emerge where neighbors, colleagues, and kinship networks converge, offering a structured way to save and access funds without formal banking channels. Because they are informal and highly localized, there is no central registry to consult when you search for ROSCAs near you. Instead, every opportunity to participate grows out of the everyday fabric of a community: a neighborhood center hosting conversations about money, a religious or cultural gathering where lending norms are discussed, or a cluster of small traders who rely on one another for working capital. In this sense, ROSCAs resemble a social contract as much as a financial instrument, built on reputation, regular attendance, and a shared commitment to mutual benefit. The very strength of these groups lies in their familiarity and the collective memory that comes from long-standing relationships within a locality.
To begin the journey of locating a nearby ROSCA, consider the most reliable entry points. Local community centers and religious institutions are often the first places where informal savings circles form or are hosted. A visiting member might be invited to join a cycle, or the institution may connect potential participants with trusted organizers who already know the group dynamics, rules, and repayment schedules. These connections matter because the success of a ROSCA depends on clear norms: how much is contributed, when payments are due, who manages the pot, and how transparency is maintained. In many communities, such circles are woven into the rhythm of daily life, meeting after services or during market days when participants can exchange updates about cash flow, upcoming cycles, and potential new members.
Beyond religious or community hubs, small business networks also serve as fertile ground for ROSCAs. In places where traders rely on a rotating influx of capital to stock inventories, ROSCAs can function as a dependable credit source between peers who share a language of trade and trust. Local trade associations may arrange regular savings rounds to help members weather seasonal lulls or fund small expansions. If you are part of a business network, asking a trusted peer about ongoing ROSCA arrangements can open a doorway into a group that already operates with established rhythms, incentives, and safeguards. In some regions, kinship or clan-based affiliations provide an organic structure for ROSCAs as well, with practices that resemble biaohui traditions where funds are pooled and allocated through a network that spans families or regional ties. This kinship dimension adds a layer of social accountability that can be both stabilizing and limiting, depending on the level of inclusivity the group maintains.
Digital inquiry rounds out the search. Social media platforms, local forums, and community message groups often host discussions about communal funding or ROSCA-like practices. A careful search for terms related to savings circles, rotating funds, or shared capital can reveal active groups, meeting times, and contact points. Online connectivity complements rather than replaces face-to-face trust-building; most ROSCAs transition from an initial online connection to in-person meetings where members inspect records, confirm contributions, and observe the group’s discipline. Regardless of the channel, the core principle remains: participation hinges on mutual trust, reliability, and a shared understanding of how the money moves through the circle.
As you explore options, balance openness with caution. In informal settings, safeguards like transparent ledgers, agreed-upon withdrawal rules, and clear leadership help reduce misunderstandings. Seek groups with rules that are openly stated and consistently enforced, and prefer circles that welcome new members through a transparent process with a probationary period. It is prudent to observe a few meetings before joining and to discuss what happens if a member misses a payment or if a cycle is disrupted by an unforeseen emergency. The social fabric that supports ROSCAs—relationships, reputation, and a common purpose—also demands ongoing attentiveness. You should feel comfortable asking about how the group handles conflicts, what happens if a member cannot contribute, and how the rotating payout is allocated when someone is unable to participate for an extended time.
For those ready to start the journey, a practical reminder: if you are exploring ROSCAs near you, see ROSCA near me resources. This kind of local reference can point you to established networks and trusted organizers within your area, helping you move from curiosity to informed involvement. Remember that the absence of a centralized directory is not a barrier but a cue to engage with the community, to listen, and to participate with humility. In many contexts, the strength of a ROSCA comes from the very willingness of neighbors to stand with one another, to lend and borrow in a spirit of shared progress, and to keep the circle intact through consistent participation and mutual accountability. For a broader, foundational perspective on how ROSCAs work and why they endure, you can consult a standard guide on the topic, which outlines the mechanics, benefits, and caveats of rotating savings and credit circles. External resources offer a wider lens on the practice while your local networks provide the lived experience that makes ROSCAs meaningful in daily life.
External resource: https://www.investopedia.com/articles/personal-finance/081615/understanding-roscas.asp
Near You, Yet Informal: The Quiet Architecture of Local ROSCAs
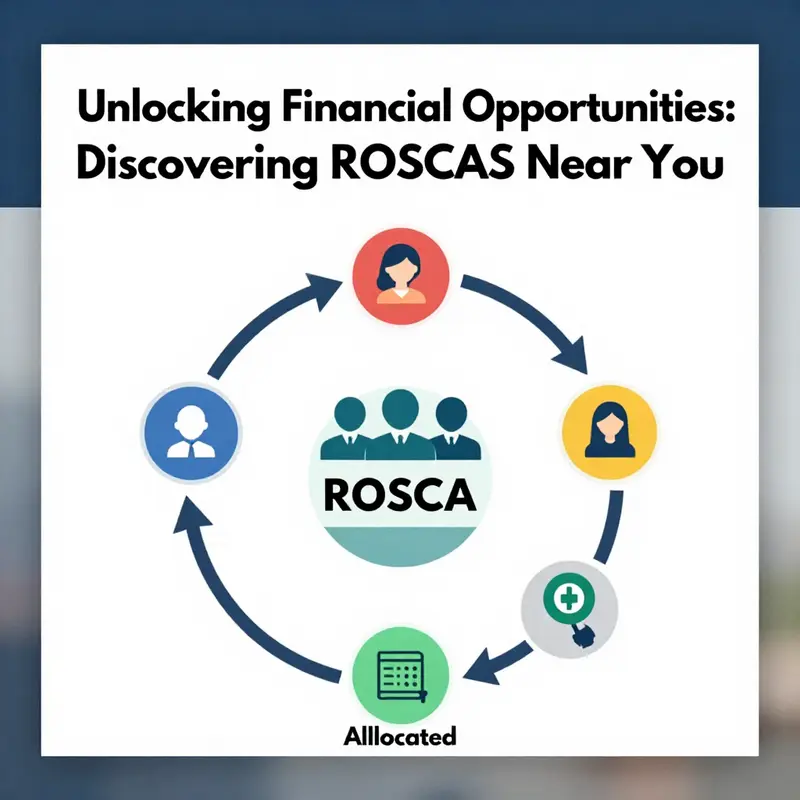
When people search for a ROSCA near me, they often expect a concrete address or a storefront. Yet the reality of rotating savings and credit associations is less about location and more about a living, local practice rooted in everyday trust. A ROSCA is a voluntary gathering of neighbors, colleagues, or kin who commit to a shared savings plan and rotate access to a lump sum. The cluster of members might meet weekly, biweekly, or monthly, and each participant contributes a fixed amount to a common pot. Over time, the pot is collected and then allocated to one member in a predetermined sequence. In practice, this means a simple ritual of discipline and expectation rather than a formal contract with courts and lawyers. The appeal lies in the immediacy: access to a sizable amount when an opportunity or need arises, without the formal banking steps that can be slow or inaccessible in many communities. The phrase near me thus points to nearby social networks and routines rather than a single, findable entity. It hints at a pattern of cooperation that travels with trust across streets, apartments, markets, and places of worship, rather than with a sign on a building.
The core structure of a ROSCA rests on two pillars: a clear contribution schedule and a predictable allocation mechanism. A typical group might have ten members who each put in a fixed sum every month. If each person contributes one hundred dollars, the pool for that cycle is a thousand dollars. The crucial moment is who receives the entire pool in the current round. There are two common formats. In a fixed-return ROSCA, the winner is chosen by a predetermined method, often a draw, and then receives the full pot. This design rewards patience and reliability; participants who consistently meet their obligations and maintain good standing are more likely to enjoy the stability of the schedule. In a bidding ROSCA, members submit informal bids to win the pot. The highest bidder wins, while the other members’ contributions effectively become the “interest” paid to the winner. This arrangement can offer higher liquidity and flexibility, but it also invites sharper competition and greater risk if members become unable to meet their commitments. Either way, the discipline comes from the social fabric surrounding the group rather than formal enforcement. There is no sovereign authority ready to step in with penalties; instead, the cost of falling out of trust falls on reputation, reciprocal obligation, and the fear of social sanction within the circle. This is why social capital—the strength of relationships, shared history, and communal norms—holds such resilience in ROSCAs.
To find a nearby ROSCA or learn if one exists in a local network, the search usually goes beyond a single directory. Community centers, women’s associations, and immigrant-support organizations can be gateways to active groups or similar savings circles with comparable terms. Family networks and kinship lines—whether tied to a local clan, a neighborhood, or a regional association—often maintain informal funds that operate with nearly identical logic to ROSCAs, sometimes under names like “biaohui” or other traditional terms that reflect collective discipline. In the digital age, social media and local forums can surface posts about ongoing meetings, shared calendars, or announcements about new rounds. While this informal nature makes ROSCAs powerful and accessible, it also calls for careful scrutiny: verify the group’s legitimacy, confirm whether all participants clearly understand the terms, and watch for red flags that indicate a high risk of default or misrepresentation.
For readers seeking a concrete example of how such groups function in real communities, a nearby resource can offer a window into everyday practice. See the ROSCA near me page for a practical sense of how groups announce rounds, how contributions are tracked, and how participants engage in a shared financial routine. This link can ground theoretical understanding in lived experience and invite further conversations with local organizers or participants: ROSCA near me. In some cases, people also explore online aggregators or local listings that flag active ROSCAs in the area: https://dulcevidabakery.shop/rosca-near-me/.
As you consider engaging with a nearby ROSCA, approach with openness to learning and respect for the social norms that sustain the framework. Ask about the schedule, the method of selecting recipients, and the process for handling missed payments. Seek clarity on any partner roles within the group, such as treasurers or rotation officers, and ensure there is a transparent way to address disputes. The value of ROSCAs lies not merely in the funds they accumulate, but in the trust they cultivate and the communities they knit together—sharing risk, pooling resources, and building a practical bridge between everyday savings and urgent needs. This chapter moves forward by exploring how local networks interact with formal financial systems, and how individuals navigate between trust-based allocations and the broader landscape of community finance.
External reading: https://www.researchgate.net/publication/308495775UnderstandingROSCAAGuidetoRotatingSavingsandCreditAssociations
Locating Neighborhood ROSCAs: A Practical Guide
In many communities, savings circles operate as informal, face-to-face networks that rely on trust and regular participation rather than formal banking channels. ROSCAs can be found where neighbors gather, share information, and support one another’s financial goals. Because these groups are typically informal and local, the search for them begins with people and places that already sustain the community.
Start with the places that anchor a neighborhood: community centers, neighborhood associations, religious organizations, and service groups. These hubs often host meetings, workshops, or social events where participants learn about savings circles and where newcomers can express interest. A staff member or volunteer who has seen regulars in the room may also hear about new cycles or established circles seeking fresh members. The path from curiosity to participation is not usually a single step; it usually involves listening, observing, and asking thoughtful questions about how the group operates, its rules, and how it safeguards trust.
Beyond formal spaces, local nonprofits and social services networks that focus on financial inclusion or community development can be gateways to ROSCAs. Staff there may offer introductions or point you to meetings where newcomers are welcome. Frame inquiries around shared goals—saving for education, health costs, or small business needs—rather than presenting yourself as a consumer shopping for a loan. This framing respects the relational nature of ROSCAs and signals a willingness to participate responsibly, which often matters to current members.
In the digital realm, a careful, local-focused approach can supplement face-to-face outreach. Local forums and neighborhood groups on social media may host threads about community savings circles or culturally specific names for group lending. The absence of a central directory is not a barrier; it just calls for patience and respectful engagement with informal channels. When you encounter a circle, listen more than you speak, learn the cadence of contributions, disbursement schedules, and how the group handles defaults or exits. Observing first helps protect both your interests and the group’s cohesion.
Kinship networks and cultural circles sometimes host savings arrangements that resemble ROSCAs, sometimes under different local names. In many communities, family networks or neighborhood associations organize rotating funds that rely on long-standing trust and shared identity. Approaching such circles with sensitivity to cultural norms is essential to building rapport and ensuring participation feels safe and voluntary. If a group is publicly listed or veteran members vouch for you, that endorsement can ease your entrance.
Practical takeaway: pursue ROSCAs not as a transaction but as a way to weave into a local savings culture. If you wish to explore near you, start by visiting community pages or resource directories that highlight neighborhood finance groups and often note opportunities to participate. This local immersion—listening first, then contributing—helps ensure your involvement strengthens instead of disrupting the social fabric that sustains these informal financial circles. When in doubt, attend a trial meeting or contact a group for an introductory conversation to observe the dynamics before committing.
Final thoughts
Engaging with ROSCAs can transform the way business owners manage their finances and grow their enterprises. By participating in these community-driven savings and credit associations, entrepreneurs can leverage the collective strength of members to access credit, develop savings habits, and build a network of support. Ultimately, the resilience fostered through ROSCAs not only benefits individual businesses but enriches the community as a whole, creating a thriving economic ecosystem. Embrace the opportunities that lie in your local ROSCA and take your business to new heights.